
Filter & sort
The OOS Tracker's controls bar: filter tracked portfolios by name, hide thin or partly mapped ones, and sort by any metric — with withheld values always last.
Once you have more than a handful of saved portfolios, the tracker list needs ordering. The controls bar sits between the count line and the list. Every control works on the summary already loaded — changing one never refetches — and the count line switches to N of M portfolios shown the moment a filter narrows the list.

Filter by portfolio name
A case-insensitive substring match on the portfolio name: ladder finds
Conservative ladder, MEIC finds every portfolio with MEIC in its name.
Leading and trailing spaces are ignored. Clearing the field restores the full
list. Only portfolios that already have at least one out-of-sample session
are in the list to begin with; the too-recent ones are counted in the line
above it.
Sort
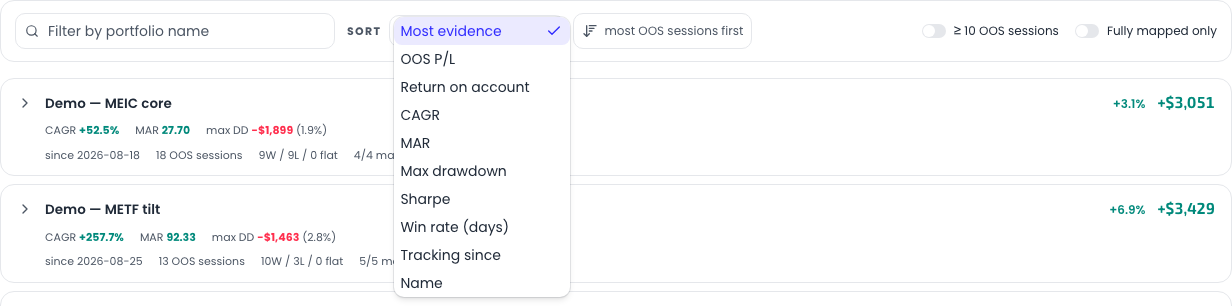
The Sort menu takes one key; the button beside it flips the direction and spells out what the current direction means for that key, so descending never has to be guessed:
| Sort key | Descending means | Ascending means |
|---|---|---|
| Most evidence (default) | most OOS sessions first | fewest OOS sessions first |
| OOS P/L | highest first | lowest first |
| Return on account | highest first | lowest first |
| CAGR | highest first | lowest first |
| MAR | highest first | lowest first |
| Max drawdown | deepest first | shallowest first |
| Sharpe | highest first | lowest first |
| Win rate (days) | highest first | lowest first |
| Tracking since | newest edit first | oldest edit first |
| Name | Z → A | A → Z |
Three rules behind the order, stated because they decide what lands on top:
- Most evidence is the default and the only sort that never puts a — first. It is the order the tracker opens in: most out-of-sample sessions first, ties broken by name. A portfolio with 18 sessions of record outranks one with 4, regardless of P/L.
- A withheld metric always sorts last — in both directions. A blank is not a value. Sorting by CAGR puts every portfolio that shows a CAGR first, best to worst (or worst to best), and the portfolios whose CAGR is withheld — under 10 sessions, or no account size — after them, whichever direction you pick. Flipping the direction never promotes a — to the top.
- Max drawdown sorts by dollar magnitude. Deepest first is the largest peak-to-trough in dollars. Dollars rather than percent so that a portfolio without a saved account size (which has no percent) still takes its place in the order.
Ties on any key break by evidence (more OOS sessions first), then by name.
The two switches
≥ 10 OOS sessions hides every portfolio under the evidence floor — the same floor that withholds CAGR, MAR, Sharpe and Sortino (see Metrics & withheld values). Turn it on when you want to look only at portfolios whose annualised numbers exist.
Fully mapped only hides every portfolio with at least one unmapped pick — one that has no shadow-universe mapping and therefore contributes $0 to the record. Turn it on when you want records that reflect the whole composition.
Both switches combine with the name filter and with each other. When nothing matches, the list says so (No tracked portfolio matches these filters) rather than going silently empty.
On the phone
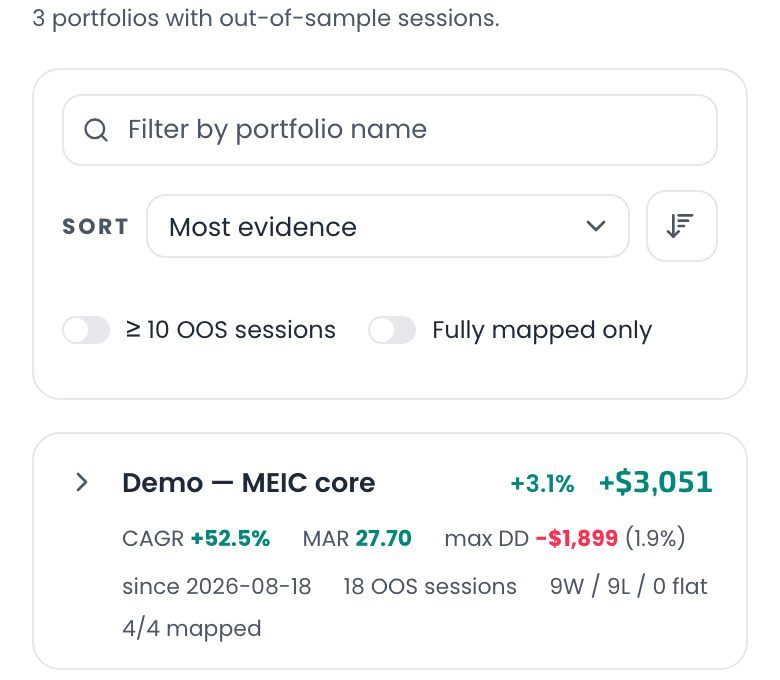
At phone width the filter takes the full row, the sort menu and direction button share the next one, and the switches wrap underneath. Every control is a real form control: labelled, keyboard-reachable, and tap targets are at least 44 px high on touch screens. The direction button shows only its icon below tablet width; its tooltip and accessible label still spell out the direction.
What the controls do not do
They do not persist. Reloading the page returns to Most evidence, descending, no filters — deliberately, so a filter left on yesterday cannot hide a portfolio today. And they do not change any number: sorting by MAR orders your portfolios, it does not grade them.
Related pages
- OOS Tracker overview
- Metrics & withheld values
- Compare — for putting up to three saved portfolios side by side on backtest metrics
Get the weekly 0DTE research email
Research notes and product updates, straight to your inbox. Unsubscribe anytime.